


Waste-To-Fiber Technologies Market Research Report: Industry Analysis and Forecast
Waste-To-Fiber Technologies Market Overview
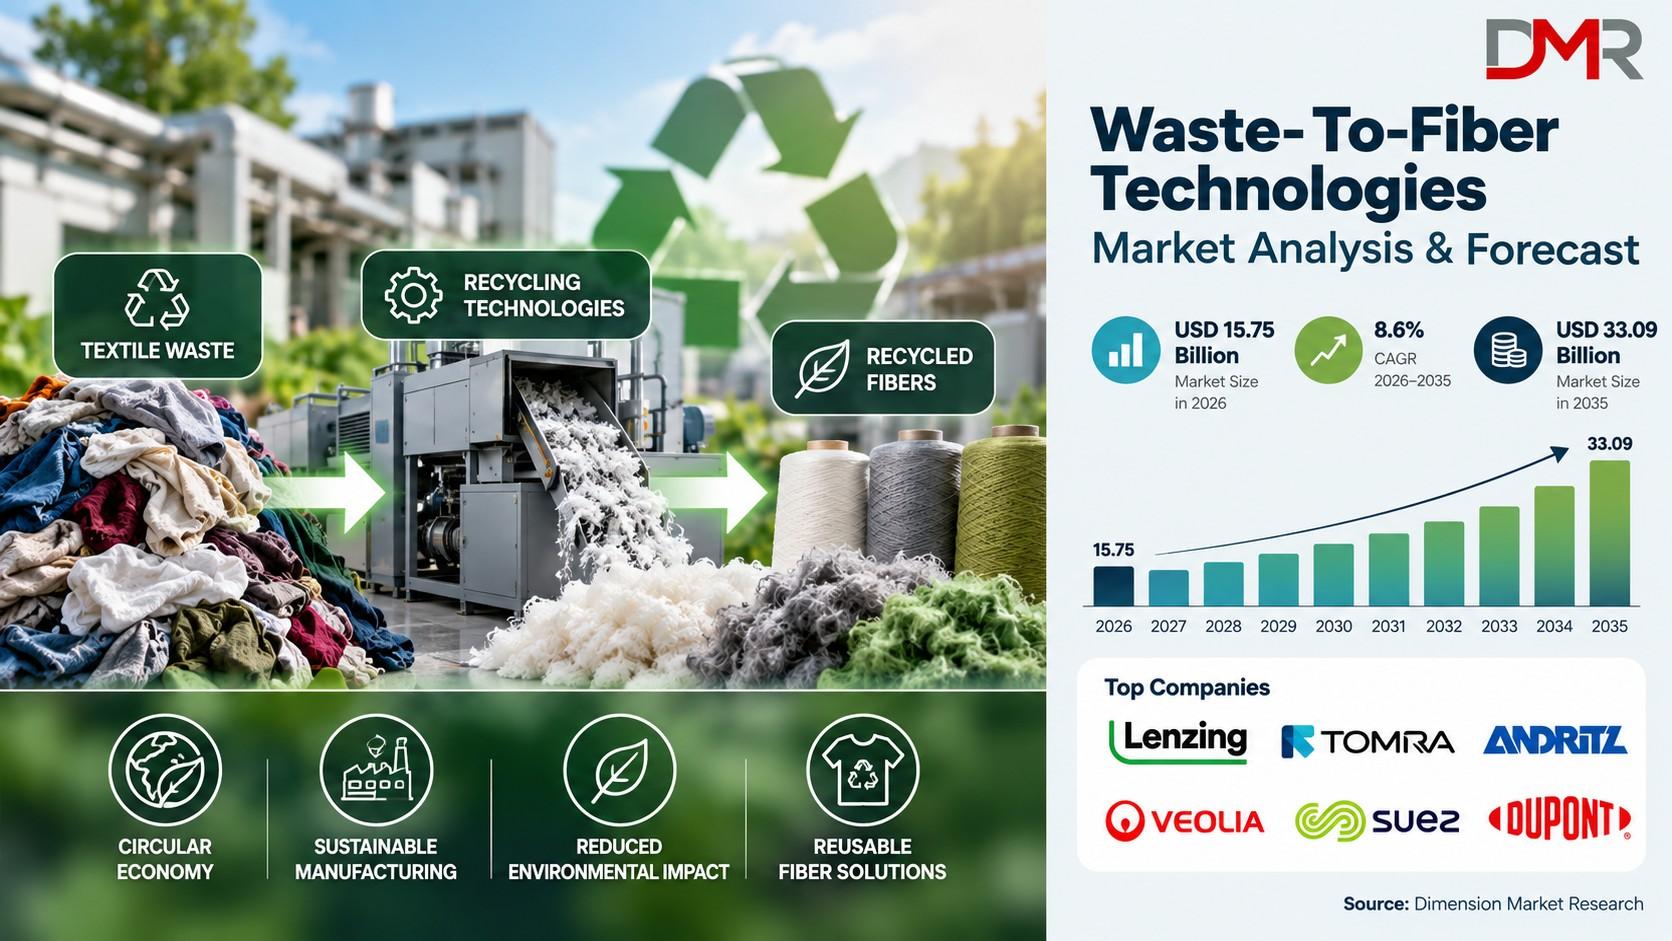
The global Waste-To-Fiber Technologies Market is gaining momentum as manufacturers, textile brands, and recycling companies seek commercially viable ways to convert textile and agricultural waste into reusable fibers. According to Dimension Market Research, the Waste-To-Fiber Technologies Market size is estimated at USD 15.75 billion in 2026 and is projected to reach USD 33.09 billion by 2035, registering a compound annual growth rate (CAGR) of 8.6% during the forecast period. This expansion reflects increasing investment in textile-to-textile recycling, recycled fiber production, and circular manufacturing systems.
Waste-to-fiber technologies encompass mechanical recycling, chemical dissolution, enzymatic treatment, automated sorting, and fiber recovery equipment. These solutions help manufacturers recover valuable materials from production scraps, discarded garments, and agricultural residues. As sustainability commitments and extended producer responsibility requirements influence procurement decisions, recycled fiber is becoming an increasingly important input for apparel, home textiles, automotive interiors, and technical textile applications.
Market Snapshot
● Market value is projected to reach USD 15.75 billion in 2026.
● Market revenue is forecast to reach USD 33.09 billion by 2035.
● The market is expected to expand at an 8.6% CAGR from 2026 to 2035.
● Pre-consumer manufacturing scrap accounted for a 66.8% share in 2025.
● Synthetic fibers represented a leading 54.7% share in 2025.
● Mechanical recycling held a 60.1% share in the reported segment data.
● Textile and apparel applications represented a 60.4% share in 2025.
● Asia-Pacific accounted for a 47.8% regional share in 2025.
● Chemical and enzymatic recycling are emerging growth opportunities.
Get insight you need (request free sample)
Market Research Findings
Dimension Market Research identifies mechanical recycling, synthetic fiber recovery, pre-consumer manufacturing scrap, and textile and apparel applications as important components of the waste-to-fiber technologies market. Their established supply chains and comparatively predictable input materials support commercial deployment. However, the market is evolving beyond conventional mechanical processing as manufacturers seek higher-quality recycled fibers suitable for demanding textile applications. Chemical and enzymatic recycling technologies are attracting attention because they offer pathways for recovering materials from complex waste streams and producing regenerated fibers. The research also highlights Asia-Pacific's strong manufacturing base, increasing brand procurement commitments, regulatory developments, and investment in industrial-scale facilities as significant influences on market development. Feedstock quality, recycling economics, and capacity utilization remain essential considerations for industry participants.
Why Is the Waste-To-Fiber Technologies Market Growing?
The market is expanding because textile manufacturers face growing pressure to reduce waste, improve material efficiency, and increase recycled content in finished products. Traditional disposal methods can waste valuable textile materials, while virgin fiber production requires additional raw materials and processing resources. Waste-to-fiber technologies provide an alternative by recovering usable fibers from manufacturing offcuts, discarded garments, and other suitable waste streams. Regulatory changes and corporate sustainability targets are also encouraging investment. Extended producer responsibility frameworks can increase the financial importance of end-of-life textile management, while brands are seeking traceable recycled materials to support circular sourcing strategies. At the same time, improvements in sorting automation, chemical recycling, and fiber regeneration are broadening the range of materials that recycling facilities can process.
Market Key Growth Drivers
● Extended producer responsibility requirements encourage textile waste recovery.
● Brand commitments increase demand for certified recycled fiber inputs.
● Manufacturing scrap provides relatively clean and consistent feedstock.
● Mechanical recycling benefits from established equipment and operating expertise.
● Chemical recycling supports the recovery of higher-quality fiber materials.
● Automated sorting can improve feedstock identification and processing efficiency.
● Circular economy initiatives encourage investment in textile-to-textile recycling.
Research Scope and Leading Market Segments
The research evaluates the waste-to-fiber technologies market across waste sources, input fiber types, processing technologies, output products, end-use applications, waste generators, equipment capacities, and geographic regions. Three particularly important segments are processing technology, waste source, and end-use application because they influence operating costs, material quality, feedstock availability, and commercial demand.
1. Processing Technology
Mechanical recycling is an established processing pathway because shredding and fiber recovery equipment can be deployed across existing textile manufacturing ecosystems. It is particularly suitable for relatively clean manufacturing scraps and applications where recovered fiber specifications are compatible with the intended product. However, repeated mechanical processing can shorten fibers and reduce their strength, limiting suitability for some premium textile applications. Chemical and enzymatic recycling technologies are emerging as important alternatives for recovering materials from more complex waste streams. Chemical depolymerization and solvent-based cellulose dissolution can support the recovery of polyester and cellulosic materials, subject to feedstock composition and process conditions. Enzymatic treatment offers another approach to selective material breakdown. Although these technologies can require greater capital investment and technical expertise, demand for higher-quality recycled outputs creates opportunities for commercialization.
● Mechanical recycling remains important for established, cost-sensitive applications.
● Chemical and enzymatic methods offer potential for higher-value material recovery.
2. Waste Source
Pre-consumer waste, including manufacturing offcuts and production scraps, represents a commercially attractive feedstock because it is often cleaner and more consistent than discarded household textiles. Manufacturers can collect waste close to the recycling facility, reducing transportation and sorting requirements. Existing industrial recovery systems also help maintain predictable material flows. Post-consumer waste is gaining importance as clothing collection programs and textile take-back initiatives expand. However, used garments may contain mixed fibers, dyes, elastane, trims, and other contaminants that complicate recycling. Investments in material identification, sorting, and preprocessing will be essential to increase recovery rates and improve the consistency of recycled fiber production.
● Pre-consumer scrap supports established recycling operations and predictable feedstock supply.
● Post-consumer textiles create opportunities for expanded circular material recovery.
Read more about this market: https://dimensionmarketresearch.com/report/waste-to-fiber-technologies-market/
3. End-Use Application
Textile and apparel manufacturers are central consumers of recovered fibers because they purchase substantial volumes of yarn and textile inputs. Recycled fiber can support apparel collections, home furnishings, and other textile products, depending on quality, durability, and certification requirements. Procurement commitments from major brands can also provide recyclers with greater visibility into future demand. Automotive interiors, insulation, filling materials, nonwovens, and technical textiles provide additional opportunities. These applications can accommodate different fiber specifications and may offer alternative markets for recovered materials that are unsuitable for premium apparel. As product designers increase recycled-content requirements, end-use diversification can strengthen demand across the waste-to-fiber value chain.
● Textile and apparel applications benefit from established fiber procurement networks.
● Automotive interiors and filling materials offer opportunities for application diversification.
Waste-To-Fiber Technologies Market Dynamics
Market Trend: Textile-to-Textile Recycling Gains Attention
Textile-to-textile recycling is becoming a strategic priority for brands seeking to return discarded textiles to fiber production rather than relying exclusively on alternative waste streams. Mechanical processing continues to serve established applications, while chemical recycling and regenerated cellulosic technologies are expanding the range of potential recycled outputs. These developments can support more circular supply chains when recovered materials meet the quality, traceability, and performance requirements of manufacturers. Industrial investments also demonstrate growing interest in scaling recycling beyond pilot operations. Partnerships between technology developers, fiber producers, and apparel brands can help align processing capacity with procurement requirements. However, successful commercialization depends on reliable feedstock supply, competitive production costs, and demonstrated product performance.
Market Opportunity: Chemical Recycling and Preprocessing Infrastructure
Chemical and enzymatic recycling create opportunities for companies seeking to recover valuable materials from blended textiles and other challenging waste streams. Efficient depolymerization and cellulose recovery may expand the availability of recycled materials for applications requiring more consistent fiber properties. Preprocessing facilities also represent an opportunity because sorting, de-trimming, grading, and standardized baling can improve the quality of feedstock supplied to recycling plants. Long-term offtake agreements between brands and recyclers can help reduce demand uncertainty and support investment decisions. Regional aggregation hubs may also lower logistics costs by consolidating waste close to textile manufacturing centers. These opportunities are particularly relevant in regions where textile production is extensive but advanced recycling infrastructure remains limited.
Market Challenge: Contamination and Cost Competitiveness
Feedstock contamination remains a significant barrier to large-scale waste-to-fiber processing. Mixed-fiber garments, dyes, chemical finishes, and non-textile components can increase sorting costs and reduce recovery yields. Post-consumer materials are particularly challenging because their composition and condition vary considerably. Improving collection systems and introducing automated material identification can help address these limitations, but implementation requires investment. Competition from virgin fibers is another concern. When virgin polyester and other conventional materials become less expensive, recycled alternatives may struggle to maintain attractive margins. Recyclers must therefore balance processing efficiency, feedstock quality, energy use, and product performance. Commercial agreements and reliable demand forecasts can help mitigate market volatility, although the economics remain dependent on technology, location, and output specifications.
Regional and Country Outlook
Asia-Pacific is the leading regional market, supported by extensive textile manufacturing, concentrated waste generation, and established recycling networks. According to the supplied market research, the region accounted for a 47.8% share, valued at USD 7.53 billion in 2025. China, India, Bangladesh, and Vietnam are important manufacturing centers where proximity between waste generators and processors can improve feedstock logistics. North America is supported by brand procurement commitments, investment in recycled fiber production, and evolving textile waste policies. Europe benefits from sustainability regulations and demand for traceable recycled materials. Meanwhile, the Middle East and Africa offer emerging opportunities for collection, sorting, and recycling infrastructure as textile manufacturing activity develops. The supplied research identifies a Middle East and Africa CAGR of 8.15%. It does not provide comparable market values and CAGRs for every country or region, so additional figures should not be inferred.
Key Competitor Companies in the Waste-To-Fiber Technologies Market
The competitive landscape includes established fiber producers, recycling technology developers, equipment manufacturers, and companies building textile-to-textile recycling platforms.
● Circulose (formerly Renewcell)
● Circ
● Södra (OnceMore)
● Infinited Fiber Company
● Evrnu
● Spinnova
● TreeToTextile
● Lenzing Group
● Birla Cellulose (Aditya Birla Group)
● Sateri
● Ambercycle
● Re&Up
● Reju
● Recover Textile Systems
● Worn Again Technologies
● ANDRITZ AG
● TOMRA Systems ASA
● Dell'Orco & Villani
● Laroche
● Saurer Group
Get 10% instant discount on report purchase
Frequently Asked Questions
1. What is the projected size of the waste-to-fiber technologies market by 2035?
The market is projected to reach USD 33.09 billion by 2035, growing from an estimated USD 15.75 billion in 2026.
2. What is the expected CAGR of the waste-to-fiber technologies market?
The market is expected to register a CAGR of 8.6% between 2026 and 2035, according to Dimension Market Research.
3. Which processing technology leads the waste-to-fiber technologies market?
Mechanical recycling is a leading technology because of its established equipment base, comparatively accessible investment requirements, and suitability for manufacturing scraps.
4. Which waste source represents a major market segment?
Pre-consumer manufacturing scrap is a major segment because it generally offers more consistent material composition and lower contamination levels.
5. Why is chemical recycling important for the waste-to-fiber market?
Chemical recycling can recover valuable polymer and cellulosic materials, supporting higher-quality recycled outputs when feedstock and processing conditions are suitable.
6. Which region leads the global waste-to-fiber technologies market?
Asia-Pacific leads the market, supported by large textile manufacturing industries, concentrated waste streams, and established recycling supply chains.
7. What are the major applications of recycled fibers?
Major applications include apparel, home textiles, automotive interiors, filling materials, nonwovens, insulation, and technical textiles.
8. What challenges affect waste-to-fiber technology adoption?
Key challenges include feedstock contamination, mixed-fiber separation, capital investment requirements, processing costs, and competition from virgin fibers.
9. Which companies compete in the waste-to-fiber technologies market?
Companies include Circulose, Circ, Infinited Fiber Company, Spinnova, Ambercycle, Reju, Recover Textile Systems, and other technology and equipment providers.
10. What opportunities could shape the waste-to-fiber market through 2035?
Chemical recycling, automated sorting, textile-to-textile recycling, regional preprocessing hubs, and long-term brand procurement agreements could support market expansion.
Explore more report:
● Vibration Control System Market
● US Workflow Automation Market
●

 English
 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Greek